Attorney-at-Law

Archive for the ‘Uncategorized’ Category

FOOTNOTES

In Uncategorized on 06/10/2016 at 23:20

I’ve decided to start what may well turn out to be a desultory series of posts, picking up scraps of orders and cases, and general remarks on cases I’ve already blogged but which don’t need a dedicated post for that purpose. I’ll caption these as above-stated.

A footnote to the Medtronic case I posted yesterday, June 9. More than once Judge Kerrigan noted that IRS took an all-or-nothing approach to sustain its position. My squad leader in basic training long ago related to me many years later a lesson he learned from his platoon sergeant, while serving in the Central Highlands of a country far away: Always Have a Plan B. Litigants, please copy.

Alvin Sheldon Kanofsky, Docket No. 21815-15, filed 6/10/16, earns a Taishoff “thank you” for an offer of proof of my contention that requests for place of trial must state a connection between the place requested and convenience of witnesses, location of documents or physical evidence, place of residence or place of business of petitioner, or a similar reason.

Alvin Sheldon, accomplished rounder, decides to take his show on the road.

“…petitioner commenced this case and requested Washington, D.C. as the place of trial. In a related case at Docket No. 18162-15, petitioner requested Winston-Salem, North Carolina as the place of trial. In another related case at Docket No. 18163-15, petitioner requested Cleveland, Ohio as the place of trial, but did not file an objection to respondent’s motion to change place of trial to Winston-Salem, North Carolina. In a third related case at Docket No. 18182-15, petitioner requested Richmond, Virginia as the place of trial, but did not file an objection to respondent’s motion to change place of trial to Winston-Salem, North Carolina. Consequently, all three related cases are presently assigned to the October 24, 2016, trial calendar for Winston-Salem, North Carolina.” Order, at p. 1.

Well, IRS, tired of Alvin Sheldon’s geographic as well as juridical roundering and noting that all four  of Alvin Sheldon’s cases involve nonfiling of returns, plays the same move as before.

“… respondent filed a Motion To Change Place of Trial in this case to Winston-Salem, North Carolina, to which petitioner objected.” Order, at p. 2.

Ch J L. Paige (“Iron Fist”) Marvel sends Alvin Sheldon’s latest off to Winston-Salem to join his three cases already there, apparently without consideration of Alvin Sheldon’s objection or his desire to try that case in Our Nation’s Capital.

Might be a good thing to require a reason for choosing a place of trial.

THIS IS A MEMO?

In Uncategorized on 06/10/2016 at 00:12

The Tax Court website, presumably vetted by the Court, states: “Generally, a Memorandum Opinion is issued in a regular case that does not involve a novel legal issue. A Memorandum Opinion addresses cases where the law is settled or factually driven. A Memorandum Opinion can be cited as legal authority, and the decision can be appealed.

“Generally, a Tax Court Opinion is issued in a regular case when the Tax Court believes it involves a sufficiently important legal issue or principle.”

The “law is settled,” huh? Well, what price 144 (count ‘em, 144) pages of Judge Kerrigan’s prose in Medtronic, Inc. and Consolidated Subsidiaries, 2016 T. C. Memo. 112, filed 6/9/16.

There are eight lawyers for Medtronic, et al., and eleven (count ‘em, eleven) for IRS.

And there’s a billion, three hundred fifty million or so in deficiencies.

The Meds US sent IP to Meds Puerto Rico (PR) for purposes of manufacturing various medical devices. Should payments to PR be reallocated to Meds US per Section 482?

Meds US also entered into manufacturing deals with Meds Suisse; IRS claims either excess accrued royalties stashed in Switzerland or Meds US made payments in excess of arms’-length for goods manufactured in Switzerland by Meds Suisse. If not, IRS claims when Meds US restructured, it made transfers compensable per Section 367(c).

Thoroughly confused? If not, stand by.

Meds US made implantable medical devices, like pacemakers. If these go wrong, people die.  Meds US therefore had heavy-duty regulatory exposure and products liability exposure. It takes years to develop a product and get FDA benison. If the product thereafter maims or slays the patient, monumental liability falls on Meds US’s head, and there is no third-party insurance, so Meds US self-insured.

Meds US had a bunch of siblings, subsidiaries and related companies, all involved in this stuff.

Meds US set up first-tier subsidiaries in PR to take advantage of Section 936. When Congress phased out this unguided largesse (incidentally bankrupting the Commonwealth of Puerto Rico), US Meds organized a Swiss subsidiary to grab whatever PR had that wasn’t tax-advantaged.

PR had a lot of freedom, and ran the manufacturing operation with nearly a free hand. But FDA and foreign regulators watched them closely.

Meds US licensed its IP to PR when it set up PR. Meds US got into an infringement jumpball with Siemens, and settled by cross-licensing IP with negotiated royalty payments.

Meds US hammered out an arms’-length royalty arrangement with Siemens, which Meds US modified after entering into a Memorandum of Understanding with IRS.

PR was responsible for products liability issues. And this stuff involved ultrahazardous risk if the stuff didn’t work, and the bad will engendered thereby would trash the company’s brand.

Meantime the Swiss were manufacturing any stuff PR couldn’t, and paying royalty at same rate PR would have paid.

But various recalls affected PR, and Meds US’s competitors, chiefly Guidant (remember them?).

The IRS Memorandum of Understanding aforesaid settled IRS’s claim that the royalty arrangement with PR was too sweet. So US Meds adopted IRS’s numbers, took heavy tax hits per Section 367(d), and went forward.

Then IRS tried again, claiming the Memorandum of Understanding numbers generated excessively cheap profits to PR.

IRS and Meds US agree about arms’-length manufacturing numbers, but not about IP.

However, at close of play, it’s all about arms’-length. The critical question is how much product quality plays in determining what PR brought to the deal. IRS says PR brought little, and marketing controls; PR and Meds US says it’s all about quality and marketing means nothing without quality.

The recall evidence sinks IRS. Past recalls murdered both Meds US and Guidant, because doctors fled each time.

Judge Kerrigan: “Respondent [IRS] does not place enough emphasis on the importance of quality in the industry. The final product is the key to success. Product quality is the foundation for which implantable medical devices can be successful. A recall could make it very difficult for a company to continue to compete in the industry at the same level. A company can have a strong sales force and a creative marketing department, but these will not make a difference if the underlying product is unsafe and ineffective.” 2016 T. C. Memo. 112, at p. 102.

OK, says IRS, but quality is spread over the entire intercompany setup. PR is just the last link in the chain. Roger that, says Meds US, PR is goalkeeper, the last defense against unreliable, dangerous pacemakers that maim and slay. And blow up everyone connected therewith.

Meds US shows PR ran all the quality control ends of the show.

IRS’s expert downplayed PR’s contribution, mismatched its operations with those of the comparables he provided, and aggregated all the functions of producing Meds US’s products unnecessarily, ignoring the facts-and-circumstances test that places great value on PR’s goalkeeping functions.

Ultimately, though, neither IRS’s expert nor Meds US’s expert provided Tax Court with a meaningful method for fixing an arms’-length royalty for the IP Meds US gave PR.

So Judge Kerrigan goes with the comparable uncontrolled transaction, or CUT method. But Meds US’s expert didn’t account for variation in profit potential. So Meds US doesn’t show IRS was arbitrary, capricious or unreasonable in its adjustment of royalty rates.

Judge Kerrigan does the usual mix-and-match, and comes out with a number that matches the Memorandum of Understanding number Meds US hammered out with Siemens, but she claims it’s coincidental. And she applies the same number to the Swiss deal.

And whatever intangibles IRS claims were transferred to PR in an outward bound transaction that renders taxable that which Section 351 exempts from tax were given to PR before the restructuring, so no Section 367(d) taxation.

IRS loses a big one.

But is this really just facts-and-circumstances? Is the law really so “settled”?
GO SUE

In Uncategorized on 06/08/2016 at 17:14

I would have taken a pass on James Clement Powell and Lucy H. Powell, 2016 T. C. Memo. 111, filed 6/8/16.But there’s a twist, although it isn’t at first apparent.

It was another run-of-the-mine unsubstantiated deductions (hop-farming in Hillsborough, NC, and Section 274 car mileage, of which Judge Pugh allows JC a pittance) deficiency with an arithmetic (transposition) error thrown in.

Footing errors usually don’t figure in Tax Court cases, but since the error was mentioned in the SNOD, Judge Pugh decided she had jurisdiction. And since IRS didn’t claim the number that gave rise to the transposition error was bogus, Judge Pugh corrected the mistake. The Rule of 9 saved JC and Emily.

JC and Emily had twice been to Tax Court before, so Judge Pugh admonishes them. “Petitioners have appeared before the Court on two previous occasions and are aware of the rules requiring substantiation of their expenses.” 2016 T. C. Memo. 111, at p. 16.

It’s nice when you’re a frequent flyer and aircrew recognize you, as happened recently to a certain Principal-to-be in a Big Four accounting firm. It is less good when Tax Court Judges give you the “Here comes the Rounder” look.

But the best is saved for last.

JC and Emily want to sue IRS for damages. And in the words of a certain elected official, “Yes We Can.”

See Section 7433. Judge Pugh explains.

“Petitioners seek $25,000 and $10,000 in damages for tax years 2011 and 2012, respectively, from respondent under section 7433.  Section 7433(a) provides that a taxpayer may bring a civil action for damages against the United States in a U.S. District Court if an officer or employee of the Internal Revenue Service recklessly or intentionally or by reason of negligence disregards any provision of the Internal Revenue Code.  This Court therefore lacks jurisdiction to hear petitioners’ section 7433 claim.  See, e.g., Petito v. Commissioner, T.C. Memo. 2002-271.” 2016 T. C. Memo. 111, at pp. 19-20.

And for readers with exceptional memories, petitioner in the Petito case aforementioned appeared in my later blogpost “Save the Cutesy,” 7/1/14.

So now it’s off to The Hill Far Above, and the semicentennial gathering of a class of distinguished attorneys (not including me) who passed through that illustrious institution so long ago.

And to drink to absent friends.

FLIP THIS CONDO

In Uncategorized on 06/08/2016 at 15:27

No, this is not a promo for a new TV series I’m trying to flog, so as to become a big-time producer and avoid mortgage closings.

Here Judge Lauber tries to help struggling homeowners Michael A. Rohde & Sophia M. Rohde, Docket No. 8758-15L, filed 6/8/16, caught between the battling SOs.

The Rohdes filed timely, didn’t pay, and got the usual NITL. They went to Appeals, asked for an IA, but the SO sustained in full because the Rohdes missed some estimateds. But the Rohdes petition because, for two other years, another SO gave them a “…’Sixty Day Extension of Time to Pay,’ in part to enable them to pursue sale of a two-bedroom condominium they own in Manhattan.” Order, at p. 1.

I checked it out online, and it’s about seven blocks from where I live, so I reckon, but do not guaranty, warrant or represent, that it might bring a decent piece of change, after the liens for unpaid common charges, transfer taxes, fees and costs are dealt with.

Judge Lauber gets the parties on the blower, and here is the upshot. “Petitioners informed the Court that they were in the process of selling the condominium and that, once it is sold, they will have the funds to pay most (if not all) of their tax liabilities. Petitioners stated that their real estate agent had advised them to perform some renovation to the condominium in order to maximize the sale price, and that the construction should be completed soon, at which point the unit will be listed for sale.” Order, at p. 2.

So Judge Lauber puts the case on status track with 30-day reporting requirements.

But lest the Rohdes get too elated, “(W)e advised petitioners that, if there is no progress in the near future toward listing the condominium for sale, the Court will proceed to rule on respondent’s motion for summary judgment or, in the alternative, place the case back on a trial session.” Order, at p. 2.

Takeaway- Here’s a blueprint that might work if your clients have some equity but little cash.


NEW SHERIFF IN TOWN

In Uncategorized on 06/07/2016 at 22:44

And Just Maybe She Reads This Blog

I mean Ch J L. Paige (“Iron Fist”) Marvel (byname suggested by faithful reader FCAaficinado; sorry FCA, no prize, just fame). And I see our county American Legion has a new County Commander who is a woman. And we will be getting a woman as Department Commander in future. Who’d ha’ thunk it?

Back to work.

Y’all will remember the petition-before-SNOD gambit. IRS bombards taxpayer with letters, none of which is an official SNOD (but remember there is no mandated form for a SNOD, just written statement of year, amount and statutory basis for tax). Taxpayer, drawn offside, petitions. IRS then drops SNOD, claims there’s no jurisdiction as petition filed before SNOD. Then petition dismissed, too late for taxpayer to petition afresh.

Tax Court judges have danced around this on numerous occasions, and I’ve blogged many such, where letters or even Ownership Disclosures were declared to be defective petitions post-SNOD, the old docket number being erased and a new docket number assigned, with direction to petitioner to serve amended petition (actually old petition reprised).

But I did wonder about the sixty-buck filing fee. If old petition dismissed (assuming fee paid therewith), must new petition incur a new filing fee? No order or opinion I could find makes this clear.

See my blogpost “Fake Out – Part Deux,” 6/23/15, wherein I suggested “Takeaway—File early, file often. If IRS gives you the wrong advice, file anyway. When they get around to sending the SNOD, file again and apply for a filing fee waiver based on earlier filing provoked by IRS misinformation. Maybe misleading info can’t confer jurisdiction, but it could save you sixty bucks, maybe.”

Well, Ch J L. Paige Iron Fist explicitly waives the filing fee in Margie Olivo, Docket No. 8720-16, filed 6/7/16. No preamble, no explanation, just the flat statement that the fee is waived. So I can’t tell if Margie asked for the waiver or Ch J L. Paige Iron Fist waived it sua sponte.

I await enlightenment, as Ch J L. Paige Iron Fist promised us a separate order detailing at length the reasons for bouncing Margie’s first petition.

Interesting though that may be, I’d also like to see Ch J L. Paige Iron Fist expatiate on waivers of filing fees in such cases.

Finally, I again implore the Tax Court judges to designate these gems. The two designated hitters today raised no novel points. And after a mortgage closing and a big lunch to encourage more business from that source, and a meeting of the Legion, I’d appreciate finding an interesting order to blog without going through 170 uninteresting ones.

“PAID HUNDREDS OF DOLLARS”

In Uncategorized on 06/06/2016 at 16:10

Larita K. Mallory’s cri de cœur doesn’t move Judge Morrison in Kenneth L. Mallory and Larita K. Mallory, 2016 T. C. Memo. 110, filed 6/6/16.

Ken plunked down heavy bucks thirty years ago for a modified single premium variable life insurance policy. You’ll remember these have a stock-market gambler’s-choice feature, whereby if the invested premium makes money, cash surrender and cover go up. But if the investment tanks, you pony up the actuarial value or lose it all.

Ken hit it big, but borrowed big. He was supposed to pay interest on his borrowing, but never did. He testifies his borrowings were all for living expenses.

Ultimately the sum of Ken’s borrowings plus interest accrued but unpaid overtook cash surrender, so the insurer dumped the policy, treated the wiped out debt and interest as a Section 72 distribution, and gave Ken a 1099-R.

Hence Larita’s handwritten note to IRS on the 1099: “Paid hundreds of $.  No one knows how to compute this using the 1099R from Monarch–IRS could not help when called–Pls send me a corrected 1040 explanation + how much is owed.  Thank you.” 2016 T. C. Memo. 110, at p. 6.

Now this gambit might have worked if Ken and Larita filed timely, which they didn’t, and heeded the advice of the Liberty Tax Service person they consulted, who “…told Larita Mallory that she ‘was going to owe a bunch of money’.” 2016 T. C. Memo. 110, at p. 6. And were readers of this my blog.

Remember Jeff Furnish? No?  Well, see my blogpost “Ambiguity is the Best Policy – Redivivus,” 10/23/13. Jeff did it right. Ken and Larita didn’t.

The insurer “…regularly issued Kenneth Mallory several types of statements relating to the policy and the loans, including:  (1) loan activity confirmations for each loan when the loan was made, (2) yearly notices requesting payment of interest and notifying Kenneth Mallory that any unpaid interest would be capitalized, and (3) quarterly reports of the policy debt and the cash value of the policy.  The Mallorys received these statements.” 2016 T. C. Memo. 110, at p. 5.

What Ken and Larita didn’t do was save every statement, find a number-cruncher with a killer instinct, and have said person go over every minute of the last thirty years looking for any discrepancy. It might cost a “bunch of money,” but would likely be cheaper than the chops Ken and Larita got.

Ken and Larita argue the interest should be deductible, but it was personal interest, and falls into none of the categories blessed by Section 163(h).

Section 72(e)(5)(A) sinks the Mallorys. The borrowings were just that, nontaxable.  When the insurer wrote them off, that was income to Ken and Larita. Plus late-filing and the five-and-ten chop.


CPA = USTCP?

In Uncategorized on 06/06/2016 at 15:15

Ch J L. Paige (still accepting suggestions for byname) Marvel gets a letter from a CPA saying the petitioner wants to close the case because he got a “no change” letter from IRS.

So Ch J L. Paige (watch this space) Marvel treats this as a “Motion for Entry of Decision on Behalf of Petitioner John E. Cox by E., C.P.A.” And IRS is directed to respond. (Name omitted.)

The order is John E. Cox, Docket No. 10207-16S, filed 6/6/16.

So what’s wrong with this picture?

Well, I did a docket search before writing this. John E. Cox is listed as “pro se.” And if E is an attorney admitted to practice before the United States Tax Court, or a USTCP, it is nowhere stated on Tax Court’s website. But if E is an attorney admitted to practice or a USTCP, shouldn’t he have filed entry of appearance? And if he had not, should not Ch J L. Paige (send in your suggestions) Marvel tell E to do so?

E doesn’t appear to be next friend or seeking appointment as such.

We all know that agents (that is, holders of Powers of Attorney) cannot appear in Tax Court. And CPAs, however otherwise credentialed, cannot appear for others in Tax Court.

So, as I have heard it expressed in certain circles, whassup wit’ that?

FOR EVERY MAN SHALL BEAR HIS OWN BURDEN

In Uncategorized on 06/03/2016 at 16:54

You too, ladies, although the exalted author of the title of this feuilleton was rather discourteous.

Anyway, that’s where The Great Dissenter, a/k/a The Judge Who Writes Like a Human Being, s/a/k/a The Inexhaustible, Indefatigable, Ineluctable, Incontrovertible, Ineffable, Implacable and Industrious Foe of the Partitive Genitive, His Honor Judge Mark V. Holmes, leaves us at the close of play in another potter’s tale, Golden State Cooperative, Inc., Docket No. 2502-15, filed 6/3/16.

E-discovery CLEs are great for geeks, and a good place to get some hours and some shuteye for the rest of us, provided only we neither snore nor rant. See my blogpost “Continuing Legal Education,” 2/22/16.

Anyway, the Golden Staters claim their enterprises do not “consist of” flogging certain flora to the medicinally-challenged, and have some summaries derived from their surveillance cameras to show their non-flogging.

Now FRE 1006 says summaries are fine, but the other side gets to eyeball the raw data whence the summaries flow.

The Golden Staters hand over flash drives that IRS’s geeks can’t open, so they ask the Golden State geeks to give them the hot flashes in such format as IRS can scope them out. The Golden State geeks say their software doesn’t talk to IRS’s software, and they can’t convert their entire IT system to make it so.

“The question here is whether producing copies of the original flash drives in the format in which they are kept is making them ‘available for examination or copying’ when the recipient cannot for technological reasons actually inspect or copy them.” Order, at p. 2.

The Golden Staters produced the raw goods, and Tax Court Rule 72(b) says usual form kept in ordinary course is good enough.

Except.

Tax Court Rule 72(a) says a party must produce in “reasonably usable form.”

“Is the language in Rule 72(a)(1) that lets the IRS ask petitioner to produce the information on IRS-compatible software amount to a requirement that it translate this information into a “reasonably useful form?” For help, we look to the Advisory Committee Notes for Federal Rule of Civil Procedure 34, the model for our Rule 72. It stresses that rules about the production of electronically stored information should ‘protect against deliberate or inadvertent production in ways that raise unnecessary obstacles for the requesting party.’ If petitioner could have produced these flash drives on Windows Media Player at little cost, we would construe Rule 72 and Federal Rule of Evidence 1006 to require it to do so. We also note that the Advisory Committee Notes observe that ‘the responding party may need to provide some reasonable amount of technical support, information on application software, or other reasonable assistance to enable the requesting party to use the information.’ Fed. R. Civ. Proc. 34 advisory committee’s note to 2006 amendment. Petitioner in this case has done so — and has even offered to try to make the footage viewable on a tablet.” Order, at p. 3.

But the Golden Staters haven’t done that yet. And where cost is involved, FRCP 34 kicks us over to FRCP 26(b)(2)(B), which says if it costs too much, the requester must pony up. The rule from back in 1974 still holds true: each party must finance its own lawsuit.

Now the Technological Age does make delivering vast quantities of information really cheap, so why do parties complain?

“But another defining characteristic of the current era is that much of this cheap information rapidly becomes costly or impossible to retrieve as advancing technology makes information stored only in legacy systems costly or impossible to access. We think the rule in such circumstances – if access can’t be had at a cost that is reasonable in the circumstances of the case (and here we note that the stakes in this case are less than $50,000) — then a responding party can do what petitioner did here; that is, offer to help with any technological problems but let the cost of making it usable fall on the requesting party.” Order, at p. 4.

So IRS doesn’t get to strike the summaries. And the techies on both sides can keep trying.

BEI MIR BIST DU SCHANE

In Uncategorized on 06/03/2016 at 16:16

No, not the Jacob Jacobs and Sholom Secunda hit that gave the Andrews Sisters their 1937 liftoff to stardom. This is a designated hitter in today’s evidentiary special, brought to us practitioners desperately seeking enlightenment by none other than The Great Dissenter, a/k/a The Judge Who Writes Like a Human Being, s/a/k/a The Inexhaustible, Indefatigable, Ineluctable, Incontrovertible, Ineffable, Implacable and Industrious Foe of the Partitive Genitive, His Honor Judge Mark V. Holmes.

And the first lesson deals with experts, their opinions and testimony. It features our friends from the day before yesterday, Patients Mutual Assistance Collective Corporation d.b.a. Harborside Health Center, et al., Docket No. 29212-11, filed 6/3/16.

The patient mutualists want to put in the reports and testimony of Sanford Schane and Henry C. Levy. IRS wants to bounce them, and trial starts Monday.

Well, despite the title of this little essay, Judge Holmes finds Schane not so schön, at least as an expert.

“Schane is a linguistics professor. He offers his opinion in his report about the meaning of the phrase ‘consists of’ for the purposes of I.R.C. § 280E, and then concludes that petitioner’s business does not ‘consist of’ dealing in a controlled substance. He also opines that petitioner’s sale of articles and offering of services is not associated with the dispensing of medical cannabis; and thus that I.R.C. § 280E should not apply to petitioner’s business.” Order, at p. 1.

That this is a nonstarter should not surprise you.

“Respondent is entirely correct that Schane’s and Levy’s conclusions are nothing more than legal opinions and thus should be excluded. Testimony on the meaning of a phrase within a statute, even by a linguist or CPA, does not concern an issue of fact. And expert opinions on law do not assist the ‘trier of fact to understand the evidence or to determine a fact in issue’ and are thus, inadmissible. Fed. R. Evid. 702(a). ‘Each courtroom comes equipped with a “legal expert,” called a “judge”.” (Citations omitted.)

Henry Levy is a CPA, and wanted to expatiate on “… several treasury regulations, sections of the Code, and subregulatory guidance to conclude that petitioner is entitled to a higher COGS adjustment than it originally reported. The interpretation of the COGS regulations is an important part of these cases.” Order, at p. 1.

You’ll recollect that the winning dodge for the medical potters is to lump deductibles as Cost of Goods Sold (COGS), which is an adjustment to gross receipts and not a deduction from taxable income, thus sliding under the Section 280E tag. The now-indicted Judge Kroupa waived home the runners, as more particularly bounded and described in my blogpost “Everybody Must Get Stoned,” 8/3/12.

So Henry Levy too might avoid being thrown out at the plate. Maybe.

“Unlike Schane, Levy may well be a useful fact witness on the quantification of COGS that petitioner actually claims, as well as issues related to respondent’s assertion of penalties. But petitioner will have to have him testify as a fact witness and not rely on his opinions in an expert-witness report.” Order, at p. 2.

Litigators please copy.

OUTCOME NEVER IN DOUBT

In Uncategorized on 06/03/2016 at 08:52

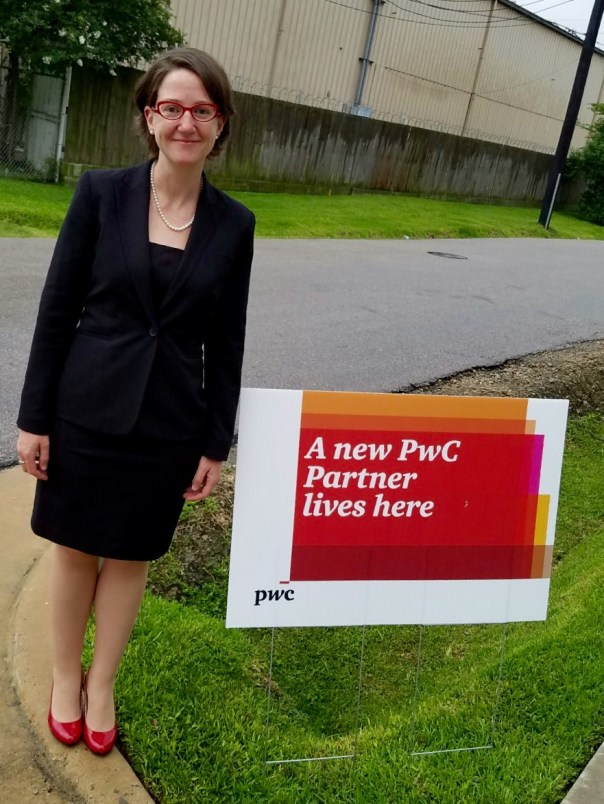
It is with monumental pride and pleasure that I announce that a Big Four accounting firm has admitted to its equity-level membership a certain graduate of the Chapin School, Rice University and the University of St. Thomas (Houston).

She is also my baby.

FullSizeRender-1